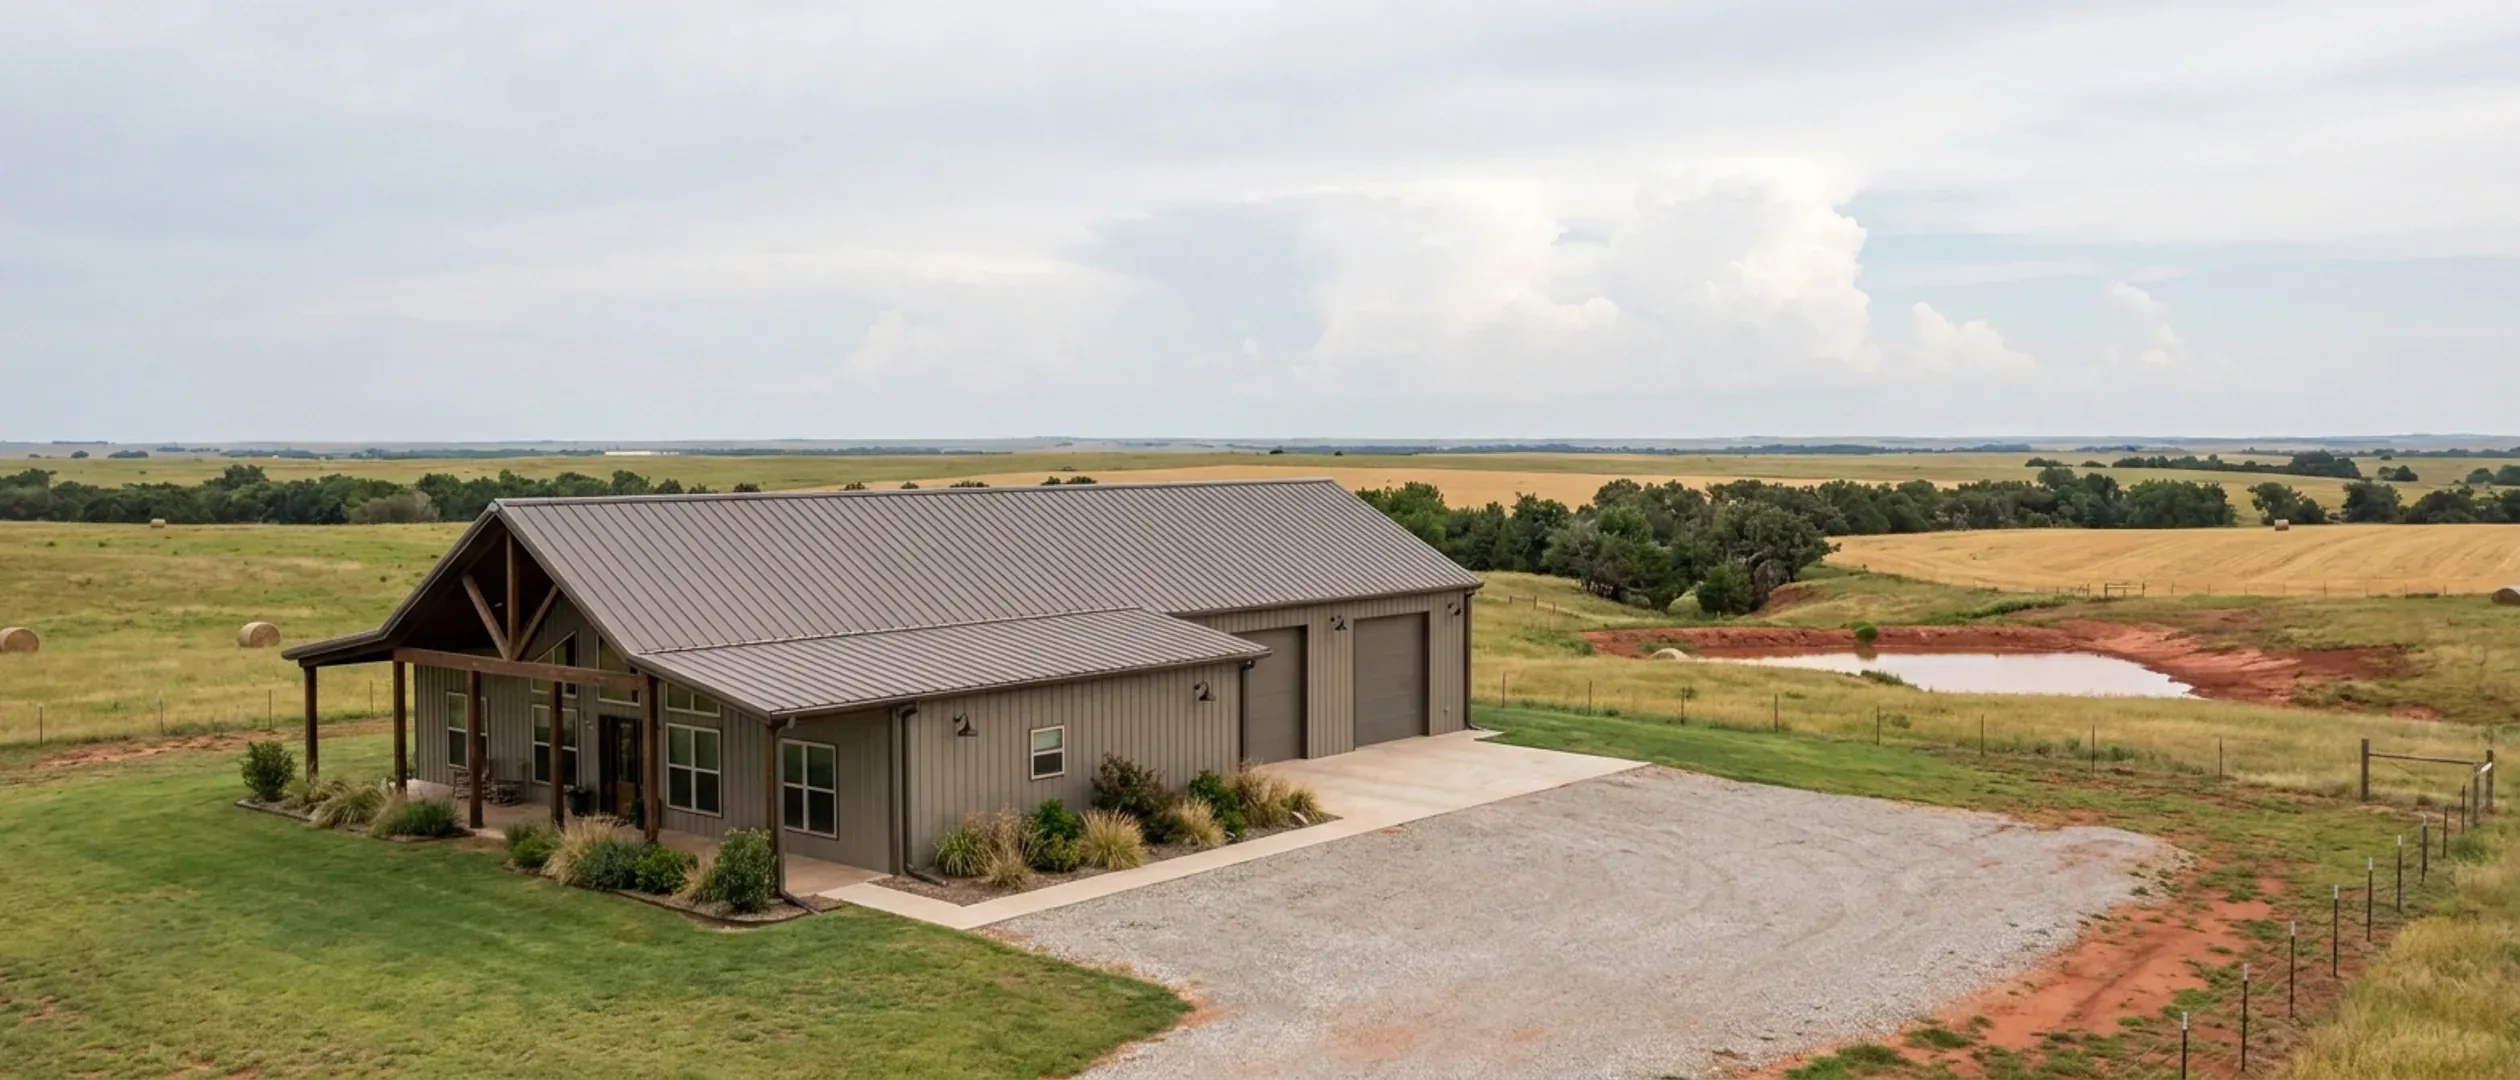
Barndominium Financing in Oklahoma: Construction Loans, Farm Credit, USDA and OHFA
A barndominium is financed the way any custom home on your own land is financed: with a construction loan that pays the builder in stages and then becomes a mortgage. What makes Oklahoma different is who lends. Two Farm Credit associations, Oklahoma AgCredit and Farm Credit of Western Oklahoma, offer rural home and construction loans across much of the state, USDA Rural Development can finance a modest new home in eligible rural areas, and the Oklahoma Housing Finance Agency offers down payment help that it says is available for new construction. This guide sets out what each source publishes about itself, with links, so you can take the right questions to a lender. We are not a lender and nothing here is financial advice.
Figures on this page are cited third-party or government data, not a quote from Oklahoma Barndominium Builders.
Bottom Line Up Front
- Most owner-built new homes are financed conventionally: the Census Bureau reports that 73% of contractor-built houses started in the South in 2025 used conventional loans, 23% were paid in cash, and FHA and VA each accounted for 2%.
- Under Fannie Mae's Selling Guide, a single-closing construction-to-permanent loan converts automatically to a mortgage when construction is complete, with no single construction period over 12 months and 18 months in total.
- Farm Credit of Western Oklahoma announced in March 2025 that, through its Rural 1st partnership, it offers construction, metal home and barndominium loans; Oklahoma AgCredit offers Rural 1st construction loans for land and home construction across 60 Oklahoma counties.
What actually moves the number
Plans and a cost breakdown
Oklahoma AgCredit asks construction borrowers for construction plans or improvement details and property details, including acreage, location and intended use. A detailed plan and budget also gives the appraiser what it needs to value a home with few comparable sales.
Land you already own
Under Fannie Mae's Selling Guide, if you own the lot before the first construction advance, the loan is a limited cash-out refinance and its loan-to-value ratio is based on the appraised value of the finished home and land. Land you own outright can supply equity toward the loan.
Interest rates
Freddie Mac's weekly survey put the average 30-year fixed mortgage rate at 7.03% for the week of 24 September 2026, up from 6.30% a year earlier. Ask each lender how it charges interest during the build.
Draw inspections
A construction lender releases money in stages as work is completed. USDA's Section 502 rules, for example, require an adult member of the household to be available to make inspections and authorize progress payments while the dwelling is built.
Construction-to-permanent loans
The standard way to finance a custom home is a single loan that covers construction and then becomes the mortgage. Fannie Mae's Selling Guide sets the rules many lenders follow.
One closing, automatic conversion
In a single-closing transaction the borrower closes on the construction loan and the permanent financing at the same time. Fannie Mae's Selling Guide says the construction loan then converts automatically to a permanent long-term mortgage when construction is complete, and the lender manages disbursements to the builder.
Twelve months, eighteen at most
Fannie Mae allows no single construction period of more than 12 months and a total construction period of no more than 18 months, with a loan term of up to 30 years after conversion. Build the schedule with that limit in mind.
If you already own the land
When the borrower holds title to the lot before the first construction advance, Fannie Mae treats the loan as a limited cash-out refinance and bases the loan-to-value ratio on the as-completed appraised value of the lot and improvements.
If you are buying the land with the loan
When the loan pays for the lot as well, Fannie Mae treats it as a purchase and divides the loan by the lesser of the total cost (construction plus lot price) or the as-completed appraised value.
Farm Credit in Oklahoma
Farm Credit associations are customer-owned lenders that finance rural homes as well as farms. Two of them publish rural home and construction lending in Oklahoma.
Oklahoma AgCredit
Oklahoma AgCredit says it serves 60 counties in Oklahoma. Through its partnership with Rural 1st, it offers construction loans for financing land and home construction, land and lot loans, and home equity loans for barns and outbuildings.
Farm Credit of Western Oklahoma
Farm Credit of Western Oklahoma says it serves 27 counties. In a March 2025 announcement from Woodward, it said its Rural 1st partnership offers purchase, construction and refinance loans, including metal home loans and barndominium loans.
What they ask for
Oklahoma AgCredit lists property details (acreage, location and intended use), construction plans or improvement details, and down payment information and financial statements where required.
Appraisal of a non-traditional home
Oklahoma AgCredit's guidance on barndominium financing notes that appraisers may need additional details or comparisons for a barndominium, and suggests having blueprints, building costs and zoning approvals ready before applying.
USDA Rural Development
USDA runs two home loan programs under Section 502. Both can finance building a new home in an eligible rural area, with conditions set in federal regulations.
Section 502 direct loans
Under 7 CFR 3550.52, Section 502 funds may be used to buy, build, rehabilitate, improve or relocate an eligible dwelling for use as a permanent residence. At loan approval the household's adjusted income must not exceed the low-income limit for the area (7 CFR 3550.53).
A modest home, not an income property
7 CFR 3550.57 requires the home to be modest for the area and not designed for income-producing purposes, and it prohibits in-ground swimming pools with new construction. A large shop used for a business can conflict with that rule.
Guaranteed loans through a lender
Under 7 CFR 3555.101, guaranteed loan funds may be used for the construction or purchase of a new dwelling, including site preparation such as grading, foundation and driveways.
Site rules that matter on acreage
7 CFR 3555.201 requires the site to be typical in size for the area and excludes property used primarily for agriculture, farming or a commercial enterprise. The site needs access from a hard-surfaced or all-weather road and adequate utilities, water and wastewater disposal.
Paying cash and mixing sources
Not every barndominium is financed with one loan.
Cash is common
The Census Bureau reports that 23% of contractor-built houses started in the South in 2025 were paid for in cash, against 73% financed conventionally.
Land loans first, construction loans later
Some owners buy land with a land or lot loan and build later. Oklahoma AgCredit offers both land loans and lot loans; when the house is built, the land becomes equity in the construction loan.
Down payment help
OHFA's Homebuyer Down Payment Assistance Program requires an OHFA lending partner and a 30-year fixed-rate loan. Ask early whether the partner can use it with a construction loan.
Rates move
Freddie Mac's survey put the average 30-year fixed rate at 7.03% for the week of 24 September 2026. A quarter-point change on a large loan is real money over 30 years, so compare lenders on rate, fees and how they charge interest during construction.
Reading this because you are weighing a build? The next step is a plan drawn for your program.
What's different about Oklahoma
Two Farm Credit associations lend on rural homes here
Farm Credit lists American AgCredit, CoBank, Farm Credit of Western Oklahoma and Oklahoma AgCredit as its institutions in Oklahoma. Of those, Oklahoma AgCredit (60 counties) and Farm Credit of Western Oklahoma (27 counties) publish rural home and construction lending through Rural 1st.
OHFA says its down payment help covers new construction
The Oklahoma Housing Finance Agency describes its Homebuyer Down Payment Assistance Program as available statewide, to first-time and repeat buyers, for new construction and existing homes, on 30-year fixed-rate FHA, HUD-184, USDA-RD, VA or conventional loans through its lending partners. Purchase price and income limits vary by product, so ask a lending partner whether it can be paired with your construction financing.
A safe room rebate is paid after the fact
The Oklahoma Department of Emergency Management's SoonerSafe rebate, up to $3,000 per home and no more than 75% of the cost, is a partial reimbursement paid after installation, and only to homeowners selected before the safe room is installed. The department's page says the 2026 program is not open at this time. It cannot be used as a down payment.
Rural site costs belong in the loan budget
Rural water benefit units, electric line extensions and septic systems are paid before anyone moves in. Lake Region Electric Cooperative, for example, requires construction costs to be paid in advance of building the line. USDA's guaranteed loan rules allow loan funds for site preparation, including grading, foundation and driveways.
Can you get a mortgage for a barndominium in Oklahoma?
What is a construction-to-permanent loan?
Does USDA finance barndominiums?
Can I use OHFA down payment assistance on a new build?
Can my land count toward the down payment?
Which Farm Credit lender serves my county?
Can the SoonerSafe rebate help pay for my build?
Questions answered? Tell us what you want to build and we will put real numbers against it.
Sources
- U.S. Census Bureau — Number of Contractor-Built Houses Started by Type of Financing (Characteristics of New Housing, 2025) — Sheet ContrStartsbyFinancing. South 2025: conventional 73%; FHA 2%; VA 2%; cash 23%. Read 26 Sep 2026.
- Fannie Mae Selling Guide — B5-3.1-02, Conversion of Construction-to-Permanent Financing: Single-Closing Transactions (05/06/2026) — Automatic conversion; 12/18-month construction period; LTV by lot ownership. Read 26 Sep 2026.
- Farm Credit — Oklahoma — Farm Credit institutions in Oklahoma. Read 26 Sep 2026.
- Oklahoma AgCredit — Rural 1st Home Loans — Construction, land, lot and home equity loans; application requirements. Read 26 Sep 2026.
- Oklahoma AgCredit — About — 60 counties in Oklahoma. Read 26 Sep 2026.
- Oklahoma AgCredit — Understanding Barndominium Financing in Oklahoma — Construction-to-permanent loans; appraisal of non-traditional homes. Read 26 Sep 2026.
- Farm Credit of Western Oklahoma — Partners with Rural 1st to Provide Financing for Home Loans (15 Mar 2025) — Construction, metal home and barndominium loans. Read 26 Sep 2026.
- Farm Credit of Western Oklahoma — About — Serves 27 counties. Read 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3550.52, Loan purposes (Section 502 direct) — Read 26 Sep 2026 via the eCFR API.
- Electronic Code of Federal Regulations — 7 CFR 3550.53, Eligibility requirements — Income limit; inspections and progress payments. Read 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3550.57, Dwelling requirements — Modest dwelling, not income-producing. Read 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3555.101, Loan purposes (Single Family Housing Guaranteed) — Construction of a new dwelling; site preparation. Read 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3555.201, Site requirements — Typical site size; agricultural property ineligible; all-weather access. Read 26 Sep 2026.
- Oklahoma Housing Finance Agency — Homebuyer Down Payment Assistance Program — New construction and existing homes; 30-year fixed; lending partners. Read 26 Sep 2026.
- Oklahoma Department of Emergency Management — SoonerSafe Program Rules & Regulations — Rebate as partial reimbursement after installation. Read 26 Sep 2026.
- Lake Region Electric Cooperative — Checklist for New Electric Services — Construction costs paid in advance. Read 26 Sep 2026.
- Freddie Mac — Primary Mortgage Market Survey, historical weekly data — 30-year fixed 7.03% week of 24 Sep 2026; 6.30% week of 25 Sep 2025. Read 26 Sep 2026.
Keep reading
The pages that answer the next question this one raises.
Cost to build a barndominium in Oklahoma
The published cost benchmarks a lender will compare your budget against.
Read itHow big a barndominium your budget builds
From a loan amount to square footage, after land and site costs.
Read itTurnkey builds
One contract from site work to move-in.
Read itPermitting
The permits and approvals a lender may ask to see before closing.
Read itWant a real number instead of a range?
Start the survey and tell us about your land and what you want to build. Include the county and parcel ID if you have them, because in Oklahoma the jurisdiction, the soil and the well and septic answers change the budget more than the building does. The survey costs nothing.